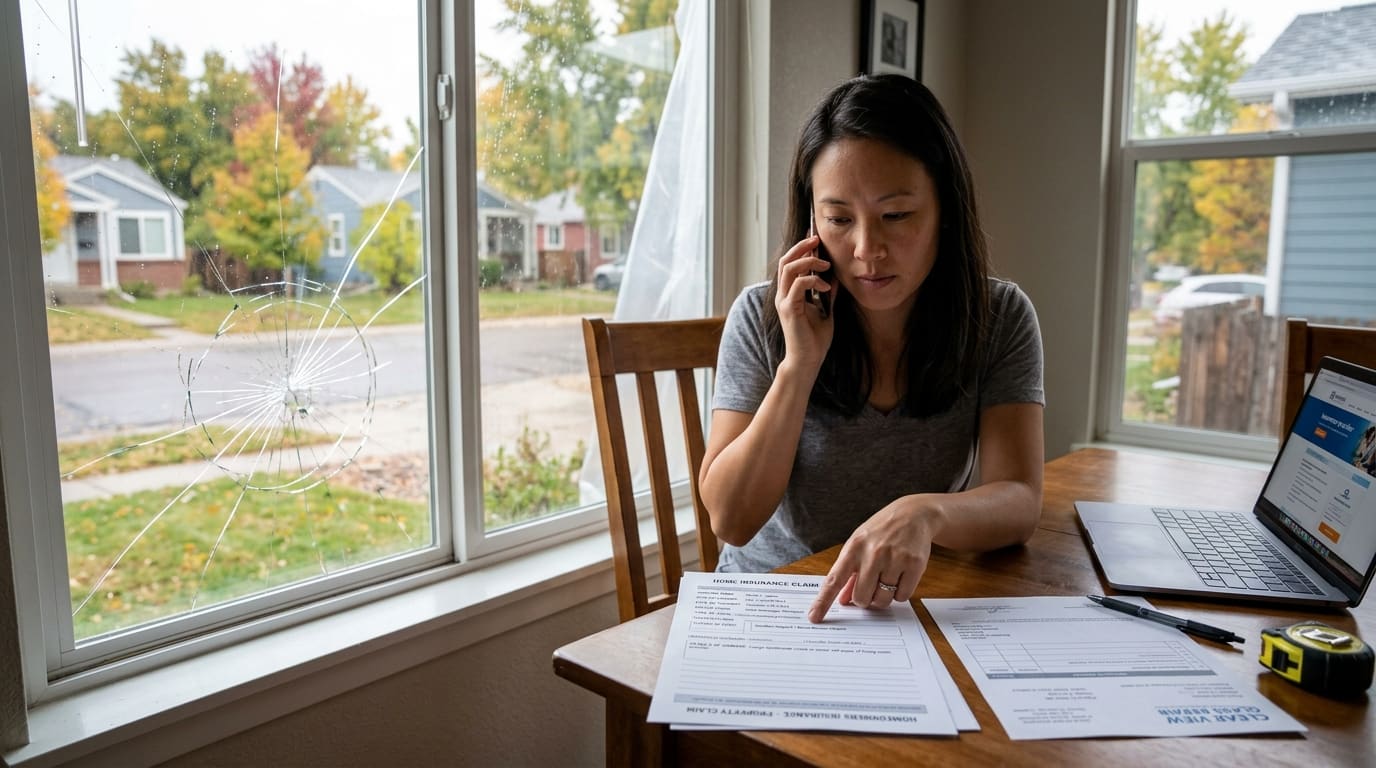
Is a Broken Window Covered by Homeowners Insurance?
Whether homeowners insurance covers your broken window depends on the cause of the damage — and the answer is often yes for sudden events, no for gradual deterioration. Here is exactly how it works.
Mike Reynolds
Lead Glass Technician & Owner
In This Article
The Short Answer: It Depends on the Cause
Whether your homeowners insurance covers a broken window is entirely about what caused the damage — not about the window itself. Sudden, unexpected events are generally covered under the "dwelling protection" or "other structures" portion of standard homeowners policies. Gradual deterioration, age-related failure, and maintenance issues are almost never covered. Understanding this distinction will help you know immediately whether a claim is worth pursuing.
What Is Typically Covered
Vandalism and malicious mischief — One of the most clearly covered perils in standard homeowners policies. If someone intentionally broke your window — whether during a break-in attempt, random vandalism, or a targeted incident — that is covered under virtually all standard policies. File a police report first; insurance companies require it for vandalism claims and it creates the official record of the incident.
Storm damage — A tree branch, flying debris, or hail that breaks a window during a storm is a covered peril in standard homeowners policies. Wind-driven debris is covered; wind alone causing a window to crack due to frame issues may be scrutinized. In the DMV area, where summer thunderstorms and the occasional derecho can be violent, storm-broken windows are among the most common glass insurance claims we help clients document.
Accidental impact — Coverage for accidental breakage (a ball thrown through a window, a contractor accidentally breaking a pane, a ladder falling against the glass) varies by policy. Some standard policies exclude "accidental breakage" unless you have added a glass rider or an "all-perils" policy. Check your specific policy language or call your agent to confirm.
Fire and smoke — Window glass broken or damaged by fire or the thermal shock from a fire is covered under the fire peril in essentially all homeowners policies.
Burglary — Window glass broken during a break-in or attempted break-in is covered under the theft/burglary peril. Again, a police report is essential for the claim.
What Is Typically Not Covered
Normal wear and deterioration — Foggy double-pane windows from failed IGU seals, glazing compound that has dried and cracked with age, and frames that have deteriorated over decades are maintenance issues, not sudden losses. Insurance companies do not cover maintenance-related failures.
Pre-existing damage — Cracks or damage that existed before your current policy was purchased are not covered. Insurers photograph windows during home inspection when possible and may deny claims for damage that appears old.
Manufacturer defects — Glass that fails due to manufacturing defect is typically a warranty matter between you and the window manufacturer, not an insurance claim.
Gradual deterioration from settling or shifting — Stress cracks from foundation settling, frame movement, or improper installation that develop gradually over time are usually excluded as maintenance or construction issues.
The Deductible Calculation
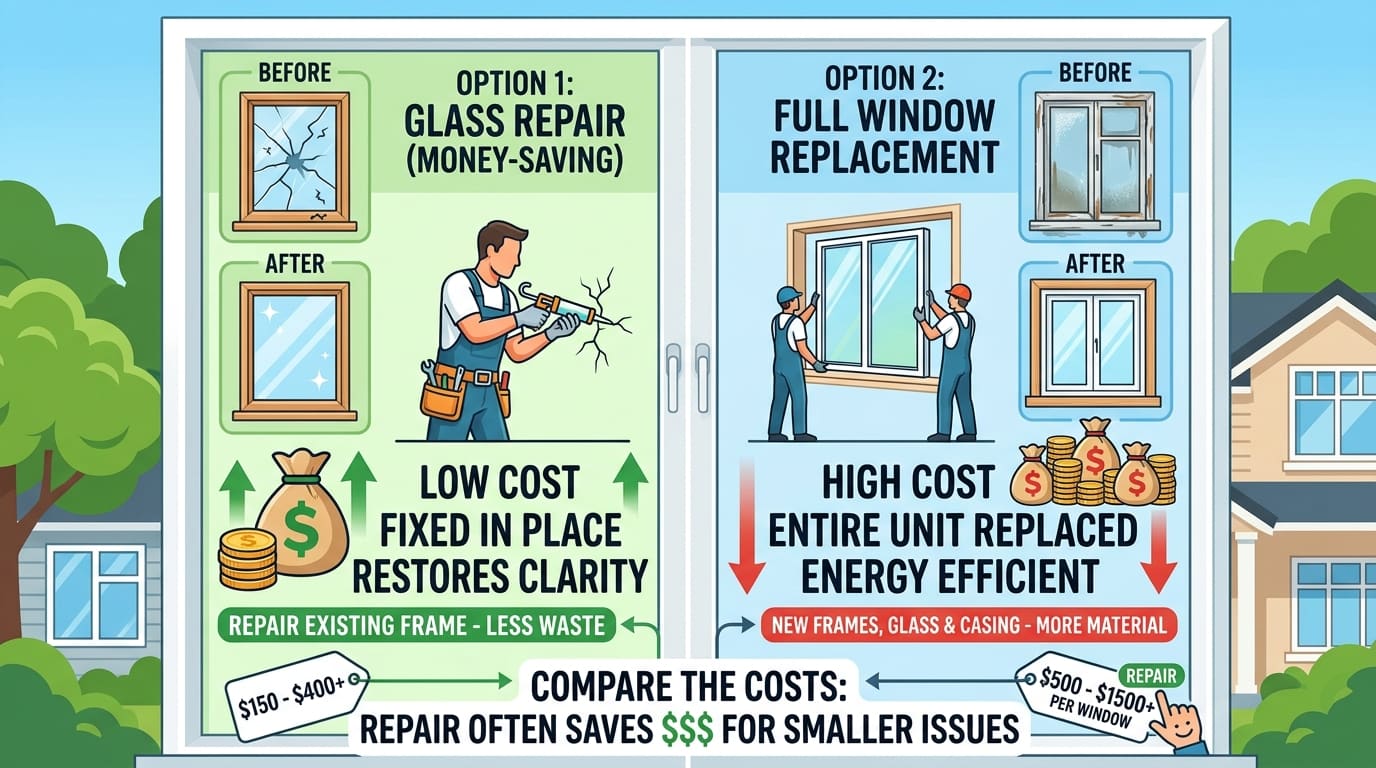
Before filing a claim for a broken window, calculate whether the claim makes financial sense. Standard homeowners policies in the DMV area have deductibles ranging from $500 to $2,500 or higher — and your actual repair cost may be at or below your deductible, making a claim pointless. Additionally, filing a claim affects your claims history, which can influence future premium rates.
For a single window replacement, it is often better to pay out of pocket and preserve your clean claims history for larger future losses. For storm events that broke multiple windows simultaneously, or for break-in damage that includes window glass plus other property damage, a claim is more likely to make financial sense after exceeding the deductible.
How to File a Glass Damage Insurance Claim
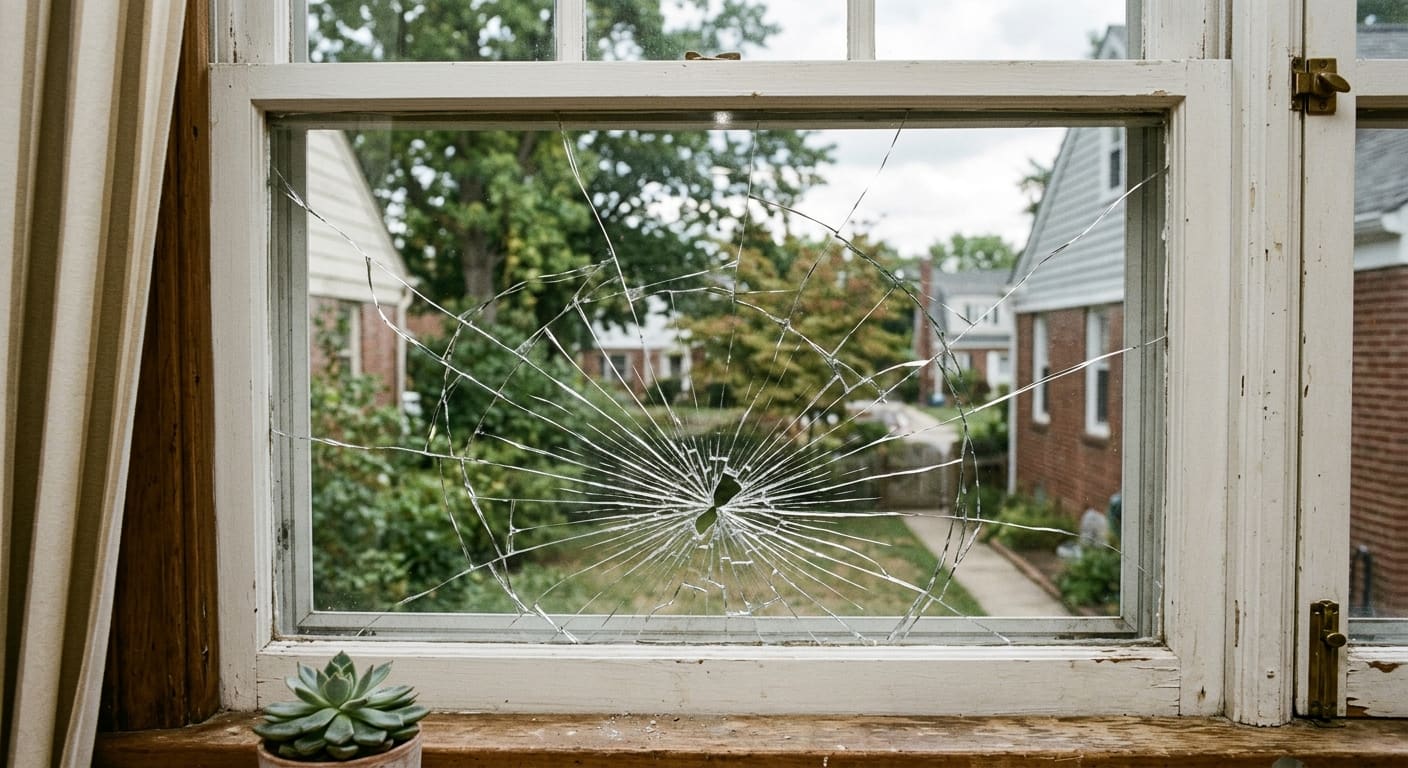
Document the damage thoroughly with photos before touching anything — wide shots showing the full window and close-up shots showing the break detail. If the cause was vandalism or burglary, file a police report and get the case number. Contact your insurance company's claims line (not your agent for active claims — call the claims department directly) to start the claim. They will assign an adjuster and may schedule a home visit or request photos and contractor estimates.
Request a written estimate from a licensed glass contractor before the adjuster's visit. Virginia Glass Windows provides detailed written estimates that insurance adjusters accept. We have direct experience working with insurance claims throughout Washington DC, Northern Virginia, and Maryland and can help you document the damage and scope of work in the format adjusters need. Call (703) 470-7867 or use our photo estimate tool to start your documentation immediately.
Third-Party Liability: When Someone Else Pays
If a contractor working on your property broke a window, their general liability insurance should cover the repair — get their insurance information and document the incident in writing before they leave your property. If a neighbor's tree fell on your window, responsibility depends on whether the tree was visibly dead or diseased (in which case the neighbor may be liable for failure to maintain it) or whether it was a healthy tree downed by a storm (generally considered an act of nature, covered by your own policy). If a vehicle struck your home and broke windows, the driver's auto liability insurance is typically responsible.
About the Author
Mike Reynolds
Lead Glass Technician & Owner
With over 15 years of experience in window and glass repair across the DC, Maryland, and Virginia area, Mike shares practical expertise to help homeowners and businesses make informed decisions about their glass repair and replacement needs.
Need Help With Your Glass?
Our experts are ready to help with any window or glass issue. Free estimates, same-day service available across DC, MD & VA.
More Guides
View All
How to Tell If Your Window Glass Needs Repair or Replacement
8 min read
Stress Cracks in Windows: Causes, Prevention & Solutions for DMV Homeowners
7 min read
Foggy Windows: Why Double-Pane Seals Fail & What to Do About It
9 min read
Glass Replacement in Historic DMV Homes: Preservation Meets Performance
9 min readExplore More Resources
Helpful Guides
Common Problems
Our Services
24/7 Emergency
Board-Up & Glass
Licensed & Insured
DC, MD & VA
300+ Areas
DMV Coverage
Same-Day Service
When You Need It
Ready to Get Started?
Get a free estimate for any window or glass service across the DMV area.